
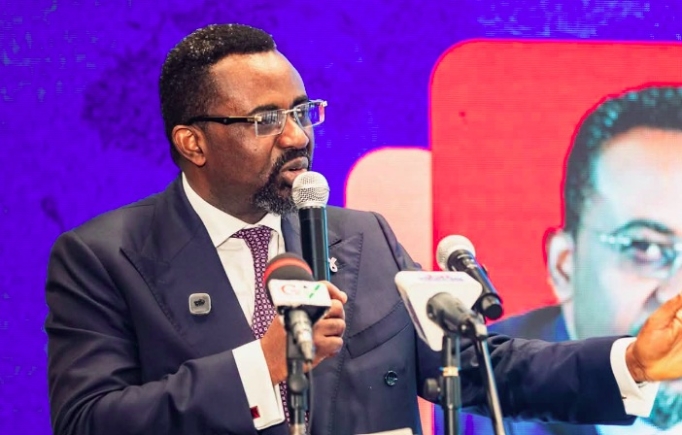
All 23 banks operating in Ghana have now met the regulatory capital requirements, the Governor of the Bank of Ghana, Dr Johnson Pandit Asiama, has disclosed, marking the completion of a recovery process that began after the Domestic Debt Exchange Programme.
Speaking at the 43rd Annual General Meeting of the Ghana Association of Banks and the launch of the sixth edition of the GH Bankers' Voice Magazine in Accra on Thursday, October 8, 2026, the Governor said the 2022 audited financial statements showed that thirteen banks had breached regulatory capital requirements as a result of the economic crisis and financial asset impairments.
"Through the collective efforts of banks, shareholders, investors, the Association, Government and the Bank of Ghana, all 23 banks have now met the regulatory capital requirements. This is a significant achievement," he said.
Dr Asiama said restoring regulatory capital was only the beginning, and that the focus must now shift to ensuring that banks maintain capital commensurate with their risk profiles and build sufficient buffers to withstand future shocks. He said this was particularly important because the risks confronting banks were becoming increasingly complex, and that boards and senior management were expected to have a clear understanding of the risks embedded in their institutions' business models.
In this regard, he said the Bank undertook a comprehensive thematic review of the viability and long-term sustainability of banks' business models in 2025. The vulnerabilities identified have been shared with the respective institutions, and engagements with boards and senior management have commenced. The Bank intends to conduct a second round of Business Model Analysis next year.
Sector performance
The Governor said the banking sector had recorded significant improvement since 2025, reflecting improved macroeconomic conditions and continued regulatory and supervisory reforms. As at the end of August 2026, total banking sector assets had increased by 20.47 per cent to GH¢500.20 billion, compared with GH¢415.20 billion a year earlier.
The sector remains well capitalised, with the Capital Adequacy Ratio improving from 18.28 per cent to 19.10 per cent, significantly above the regulatory minimum of 13 per cent. Asset quality has also improved, with the Non-Performing Loans ratio declining from 20.77 per cent in August 2025 to 15.66 per cent in August 2026.
Dr Asiama, however, cautioned against interpreting the improvement as the end of the reform journey, stating that the task now was to ensure that stronger balance sheets translate into sustainable business models, stronger risk management and greater support for productive economic activity.
Credit risk and asset quality
The Governor reminded banks of the requirement to reduce their NPL ratios to the prudential limit of 10 per cent by the end of December 2026, describing asset quality as one of the most important vulnerabilities within the banking sector. He said the Bank of Ghana issued the Notice on Non-Performing Loans in August 2025 to strengthen governance arrangements for credit risk management, establish prudential limits on NPLs and provide remedial measures in respect of wilful defaulters.
He said banks must also strengthen underwriting standards, credit administration, loan monitoring, restructuring practices, collateral management, write-offs and recovery processes, adding that increasing regulatory attention to NPLs represented a shift from simply provisioning for problem loans to ensuring that banks actively prevent, manage, recover and resolve problem assets. He said the Bank was in the process of issuing a Directive on Credit Risk Management to complement the NPL Notice.
Liquidity and stress testing
On liquidity, Dr Asiama said the Bank was in the process of publishing the Liquidity Coverage Ratio Directive, which would establish the prudential liquidity requirement for banks and mark an important milestone in strengthening liquidity regulation. He said the ratio should not be viewed as merely another regulatory figure but should form part of a broader liquidity risk-management culture supported by appropriate contingency funding arrangements, diversified funding sources and effective asset-liability management.
He said the Bank had strengthened its macroprudential stress-testing framework and had been engaging banks on the results of stress tests conducted under severe but plausible economic and financial scenarios. He said the exercises help identify vulnerabilities and assess the resilience of the banking system to shocks, and that institutions were expected to use the results to inform capital planning, liquidity management, risk appetite and strategic decision-making.
Digitalisation, Cybersecurity and AI
The Governor said cybersecurity, digital fraud, data protection, third-party dependencies, cloud computing and operational resilience were receiving increasing supervisory attention. Following the publication of the revised Cyber and Information Security Directive, he said the Bank had continued to work closely with the Association and the industry to facilitate implementation, and would undertake thematic reviews focusing on its implementation. He said boards and senior management should treat cybersecurity and operational resilience as core business risks and not simply as technology issues.
On artificial intelligence, Dr Asiama said the Bank was developing a Directive on the Use of Artificial Intelligence in the Financial Sector, which would seek to promote responsible experimentation and innovation while ensuring appropriate governance throughout the AI lifecycle. He noted that AI had the potential to improve credit assessment, fraud detection, customer service, risk management and operational efficiency, but also introduced new risks relating to data quality, model risk, cybersecurity and consumer protection.
The Governor said the question before the industry was not whether the banking sector had recovered from the crisis that led to the Domestic Debt Exchange Programme and emerged more resilient, but whether enough was being done to preserve the gains and build a sector better equipped to withstand future shocks.
He said regulation alone could not create a resilient banking sector, and that the ultimate responsibility lay with boards, management and the institutions themselves to build strong risk cultures, sustainable business models and institutions that could serve customers through both good times and periods of stress. He said the ambition should be to build a banking sector strong enough to absorb shocks, innovative enough to adapt to change and capable of financing Ghana's long-term economic transformation.