
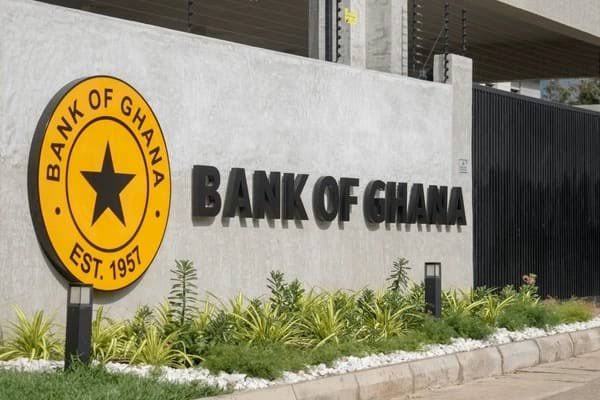
The Bank of Ghana has issued a new directive requiring all Payment Service Providers (PSPs) and Settlement Banks to hold merchant collection funds in designated settlement accounts strictly segregated from the PSPs' operational and business accounts, warning that non-compliance will attract regulatory sanctions.
The notice, signed by the Secretary of the Bank, Aimee Vyda Quashie, was issued pursuant to Section 101 of the Payment Systems and Services Act, 2019 (Act 987).
The central bank emphasised that Payment Service Providers are licensed to facilitate payment transactions and collect funds on behalf of merchants, but are not deposit-taking institutions and are therefore not permitted to hold, utilise, pledge, encumber or otherwise exercise ownership rights over funds collected on behalf of merchants.
"The funds shall remain the property of the respective merchants until settlement is effected in accordance with the terms and timelines specified in the Service Level Agreement executed between the PSP and the merchant," the notice stated.
Under the new directives, funds collected on behalf of merchants must be credited into the designated settlement account and must not be commingled with the operational funds of the PSP.
PSPs are required to settle merchant funds into the merchants' designated bank accounts strictly in accordance with the settlement periods agreed upon under the applicable SLA.
The Bank of Ghana stated that under no circumstances shall a PSP withdraw, transfer, pledge, subject to a lien, effect a set-off against, or otherwise encumber merchant funds held in the settlement account, except for the purpose of effecting settlement to the merchant and transferring duly earned fees and charges.
Settlement Banks have also been directed to ensure that settlement accounts holding merchant funds are maintained and operated solely for settlement purposes, and shall not permit a PSP to access or utilise such funds for operational, financing, investment or any other purposes unrelated to merchant settlement. The portion of merchant funds representing the PSP's agreed fees may only be transferred to the PSP's operational account as part of the settlement process.
The notice further requires PSPs and Settlement Banks to maintain adequate records, controls and audit trails to demonstrate compliance with the requirements relating to the safeguarding, segregation and timely settlement of merchant funds.
The Bank of Ghana may also require settlement banks to submit statements relating to settlement accounts used for the collection of funds on behalf of merchants, at such intervals and in a manner as may be determined by the central bank.
Failure to comply with these requirements, the Bank warned, shall constitute a breach of the applicable regulatory framework and may attract appropriate regulatory, supervisory and enforcement actions. All PSPs and Settlement Banks have been required to take immediate steps to ensure full compliance and to review their operational arrangements, agreements and internal controls accordingly.